European tech valuations stabilise, but exits remain scarce
European tech valuations settled near 5.0x in 2025, but transaction volume dropped 73%. ScaleX data on AI premiums, exits and what drives multiples.
13/11/2026
European tech valuations stopped falling in 2025. The median revenue multiple (a company's valuation divided by its annual revenue) settled close to 5.0x, after reaching 7.9x in the first half of 2022. Yet only 751 priced transactions were recorded in 2025, about 73% fewer than the 2,783 in 2021. These are findings of the ScaleX Index – European Tech Market Weather (H1 2026), which analyses approximately 9,700 disclosed transactions involving more than 8,000 European tech companies.
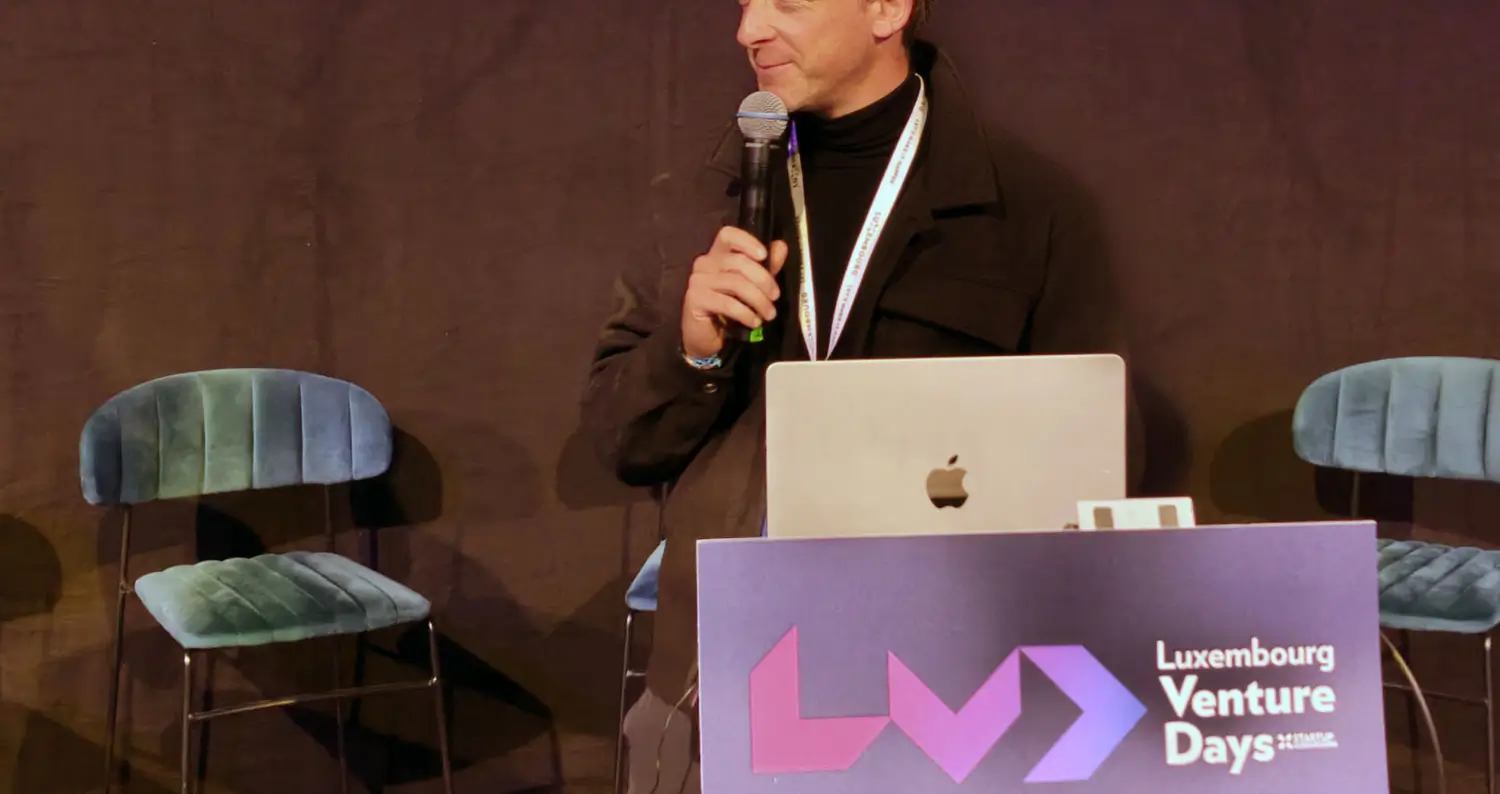
Sébastien Paillet, CEO and founder of ScaleX Invest, presented the report at Luxembourg Venture Days on 15 October. "The valuation in the tech industry has stabilised. It has been pretty steady for more than a year now," he said. "The key indicator for valuations going up again will be volume and liquidity."
How company size shapes tech valuations
Company size shapes how investors assess a business. In the second half of 2025, median revenue multiples ranged from about 8.0x for companies with less than €10 million in revenue to 2.7x for those above €250 million.
Growing does not make a company less valuable. As a business scales, its valuation depends less on potential and more on evidence such as margins, customer retention and cash generation. In the report's words, "a company can triple its revenue and watch its multiple halve".
Break-even is the riskiest stage. Companies with Earnings Before Interest, Taxes, Depreciation, and Amortisation (EBITDA) margins between 0% and 20% had a median multiple of about 2.4x. It was higher for companies with heavy losses (15.6x) and for those above a 20% margin (4.6x). "Either the company is able to scale very fast, or it generates a lot of EBITDA. The intermediary world does not work," said Mr Paillet.
AI valuations carry a premium, but the label is not enough
"AI entered the market quite rapidly, and it now has a strong impact on making valuations higher," said Mr Paillet. Companies building AI itself (models, infrastructure and chips) recorded a median of 13.1x revenue. AI-enabled software recorded 9.7x, against 5.7x for software without AI.
The report adds a caveat. Only about 7% of AI-labelled companies make AI their product, and roughly two-thirds are software businesses using it as a feature. Samples in deep tech are small, so these figures call for caution.
Funding rounds and exits diverge on price
In the second half of 2025, revenue-generating venture-backed companies raised funding at about 9.3x revenue. Venture-backed companies that were acquired sold at about 2.7x. These are different companies, so the gap is not a direct loss. It shows that a funding round and a sale test a company differently. Only 19 priced venture-backed exits were recorded across Europe in the latest window.
"The exit will also be a very important element to track, because it is driving valuations at the bottom at the moment," concluded Mr Paillet.
For the latest data on Luxembourg's startup ecosystem, explore our reports. Companies looking to scale in Luxembourg can also discover the Fit 4 Start and Fit 4 Scale programmes. Investors willing to keep up about startup's investments can register for Luxembourg Venture Days 2027.
Key findings
- Median tech revenue multiple: 5.0x (down from 7.9x in H1 2022)
- Priced transactions in 2025: 751 (–73% vs 2021)
- AI-core companies: 13.1x median multiple
- AI-enabled software: 9.7x vs 5.7x for non-AI software
- Venture-backed exits recorded (H2 2025): 19
- Break-even stage multiple: 2.4x (lowest of all profitability brackets)